The first year of a startup is full of big decisions. How much should you spend on marketing? When can you afford your first hire? Is it time to invest in new tools or hold on to cash? Accountants for startups help founders answer these questions with accurate financial data instead of guesswork. They make sure business owners know what they can afford and where their money is going.
A good accounting setup also makes day-to-day business easier. From recording the first sale and tracking startup costs to managing taxes and preparing financial reports, the right support keeps financial work from becoming a roadblock. A reliable startup accounting firm can give founders access to skilled professionals and help them build sound financial practices without hiring a full in-house team.
What You Will Learn From This Blog
- Why startups need a sound financial setup from the start.
- The key money and accounting issues new businesses face.
- How accountants for startups help manage books, cash flow, tax, and reports.
- When a startup should hire an accountant.
- Common accounting mistakes new business owners should avoid.
- How to choose the right accounting support as the business grows.
Why a Strong Financial Foundation Matters for Startups
A strong financial base helps a startup stay on track as it moves from launch to growth. It gives founders a clear view of sales, costs, cash on hand, and debt. This makes it easier to plan ahead and act before small issues turn into larger ones.
Here are some key reasons why it matters:
1. Better control over cash flow
A startup may make sales but still lack cash to pay rent, staff, vendors, or other bills. This can happen when clients pay late or costs rise faster than income. Clear cash flow records help founders see when money is due and when it is likely to come in.
2. Smarter use of funds
Most new businesses have a set budget. They must decide how much to spend on staff, tools, stock, sales, and daily costs. Good records help founders see which costs are worth the spend and where they need to cut back.
3. Easier tax and legal compliance
Startups must meet tax and filing rules based on their business type and location. Poor records can lead to missed tax dates, wrong returns, and added fees. A sound accounting setup helps keep key records ready for tax work and review.
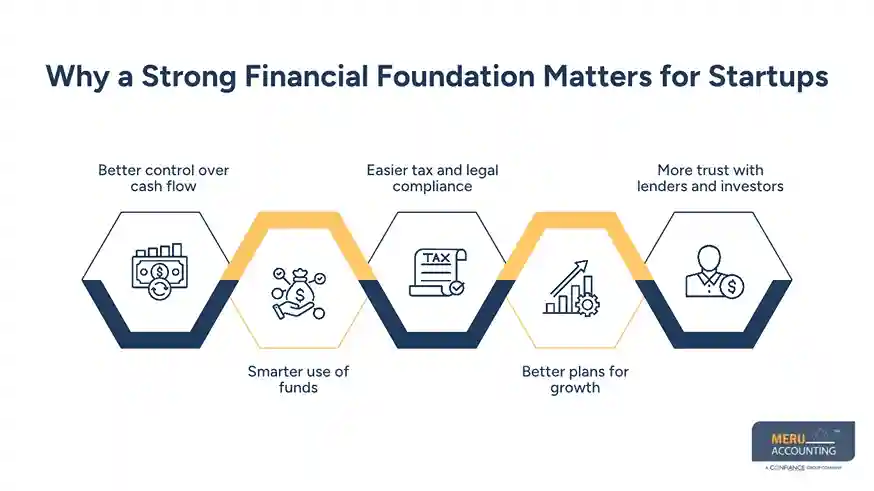
4. Better plans for growth
Founders need to know if the business can afford to hire staff, buy stock, add new services, or enter a new market. Clear reports help them test these plans before they spend money.
5. More trust with lenders and investors
Banks, lenders, and investors may ask for profit and loss reports, balance sheets, cash flow data, and tax records. Clean books make it easier to share clear and reliable data when seeking funds.
Key Financial Challenges New Businesses Face
Many startups begin with small teams and tight budgets. Founders often handle sales, client work, hiring, and daily tasks at the same time. As a result, finance work can fall behind.
Some common challenges include:
Unclear records: Mixing personal and business costs makes it hard to track true business income and spending.
Unplanned cash needs: A new firm may not have enough cash to cover rent, payroll, stock, or tax bills when they fall due.
Poor cost tracking: Small costs can add up over time. Without clear records, founders may not know which areas use the most funds.
Late client payments: Unpaid bills can limit the cash a startup needs to pay its own vendors and staff.
Tax errors: New business owners may not know which taxes apply, what they can claim, or when they need to file.
Lack of useful reports: Without a clear view of profit, debt, and cash flow, founders may base key choices on guesswork.
These issues can affect a startup at any stage. The sooner they are dealt with, the easier it is to keep the business on sound financial ground.
How Accountants for Startups Help Build a Strong Financial Foundation
Accountants for startups help founders set up the right systems and keep their money records in order. They also turn raw data into clear reports that help owners make sound business choices.
Here are the main ways they support a new business.
1. Set Up a Clear Chart of Accounts
A chart of accounts is the base of a business’s books. It sorts each entry into groups such as sales, costs, assets, debt, and equity.
An accountant can set up these groups based on the startup’s business model. For example, an online store may need separate accounts for stock, shipping, payment fees, and sales returns. A tech startup may need clear groups for software costs, staff pay, and product work.
A well-set chart of accounts makes it easier to track costs and build useful reports.
2. Manage Bookkeeping and Daily Transactions
Bookkeeping means recording the money that comes in and goes out of a business. It covers sales, bills, bank entries, staff costs, and other daily activity.
Accountants help keep these records up to date. They also match bank and card entries with the books to find missing or duplicate items. This helps founders spot errors early and avoid a backlog of work at tax time.
3. Create Budgets and Track Cash Flow
A budget sets out how much a startup plans to earn and spend over a set period. A cash flow plan shows when money is likely to come in and go out.
Accountants help founders build both plans using past data, sales goals, and known costs. They can also review actual results against the budget to show where the business is over or under plan.
This helps owners plan for slow sales, late payments, and high costs before they affect daily work.
4. Manage Accounts Payable and Receivable
Accounts payable tracks the money a business owes to vendors. Accounts receivable tracks the money clients owe to the business.
Accountants help keep both sides in order by recording bills, tracking due dates, sending or checking invoices, and reviewing unpaid balances. They can also help set payment terms and follow-up steps.
This work helps startups pay vendors on time while taking steps to collect money from clients sooner.
5. Handle Payroll and Tax Compliance
As a startup hires staff, payroll becomes more complex. The business must track hours, wages, tax withholdings, and other pay details. It must also meet payroll tax filing and payment rules.
Accountants help set up payroll records, review pay data, and support tax filings. They can also help track business tax costs and keep the records needed for year-end returns.
Tax needs vary by business type and location, so founders should seek advice based on their own setup.
6. Prepare Financial Statements and Reports
Financial reports show how a business is doing. The three main reports are:
- Profit and loss statement: Shows income, costs, and profit or loss over a set period.
- Balance sheet: Shows what the business owns, what it owes, and the owner’s equity at a set date.
- Cash flow statement: Shows how cash moves in and out of the business.
Accountants prepare and review these reports so founders can see the full picture. They can also explain key changes, such as a rise in costs or a drop in cash.
7. Support Financial Planning and Business Growth
As a startup grows, its money needs change. It may need to hire more staff, buy stock, raise funds, or add new sites.
Accountants help founders review the cost and cash needs of these plans. They can build forecasts, review profit margins, and assess how changes in sales or costs may affect the business.
This helps owners make growth plans based on real numbers rather than estimates.
When Should a Startup Hire Professional Accountants?
There is no fixed time when every startup must hire an accountant. Some need help before they make their first sale, while others can manage basic records for a short time. The right time depends on the business model, number of transactions, tax needs, and plans for growth.
Here are some signs that a startup may need professional accounting support:
- The business is making regular sales: More sales mean more invoices, payments, costs, and tax records to manage.
- Cash flow is hard to track: If founders cannot tell how much cash is free to spend, they may need help with cash flow reports and forecasts.
- The startup is hiring staff: Payroll brings new tasks, tax duties, and filing dates.
- The business plans to raise funds: Investors may ask for clean books, financial reports, and forecasts before they review a funding request.
- Tax work is taking too much time: If founders are unsure about tax rules or filing dates, an accountant can help keep the business on track.
- The books have fallen behind: Missing entries, unpaid bills, and unmatched bank records can make it hard to know the true state of the business.
A startup does not need to wait until these issues become serious. Getting help early can save time and reduce the risk of costly errors.
optional anymore
on running the business
Common Accounting Mistakes Startups Should Avoid
Many new business owners learn finance as they run the business. But a few early mistakes can affect cash flow, tax work, and future growth. Here are some common issues to watch for:
1. Mixing personal and business funds
Using one bank account for both makes it hard to track business costs and prove which expenses belong to the company. Open a separate business account and use it for all business activity.
2. Ignoring bank reconciliation
A bank balance may not match the books due to pending payments, bank fees, duplicate entries, or missing items. Reconcile accounts each month to find and fix these gaps.
3. Recording income only when cash arrives
Under the accrual method, income is recorded when it is earned, not just when payment comes in. This gives a clearer view of sales and unpaid invoices. The right method depends on the business and its tax needs.
4. Setting prices without knowing costs
A startup may price its goods or services based on what rivals charge. But if it does not track labor, stock, shipping, and overhead, it may sell at a loss. Review the full cost of each product or service before setting prices.
5. Waiting until tax season to sort the books
Leaving months of entries for one big cleanup makes errors harder to find. Keep records up to date and review them each month.
6. Treating profit as cash in the bank
A business can show a profit and still lack cash to pay its bills. Unpaid invoices, stock purchases, loan payments, and other cash needs can cause this gap. Review both profit and cash flow before making spending choices.
Build a Strong Financial Base for Your Startup With Meru Accounting’s Professional Accounting Services
A startup’s accounting needs change as it moves from its first sale to regular operations and plans for growth. Early on, the priority may be setting up the books and tracking initial expenses. Later, the business may need tighter control over vendor payments, payroll, tax records, and monthly financial reports. At Meru Accounting, we provide outsourced accounting support that helps startups manage these needs at each stage.
Our accounting professionals bring experience across multiple industries and handle the financial tasks that help keep a business on track. Our services include:
- Bookkeeping and account setup: Organizing financial records, setting up accounts, recording transactions, and reconciling bank and credit card statements.
- Cash flow and expense tracking: Monitoring income, operating costs, unpaid invoices, and upcoming payments to help founders plan their cash needs.
- Accounts payable and receivable: Managing vendor bills, customer invoices, payment records, and outstanding balances.
- Payroll accounting: Maintaining payroll records and tracking wages, deductions, and related liabilities.
- Tax preparation support: Organizing financial data and preparing records needed for business tax filings.
- Financial reporting: Preparing profit and loss statements, balance sheets, and cash flow reports to help owners assess business performance.
- Cleanup and catch-up bookkeeping: Correcting gaps in past records and bringing overdue books up to date.
Our approach goes beyond recording transactions. We focus on keeping financial data organized, reviewing entries for accuracy, and preparing reports that founders can use to make business decisions. Our dedicated accounting teams follow quality-control and review processes to maintain consistency as transaction volumes and business needs change.
With Meru Accounting, startups can access trained accounting professionals without the cost of building a full in-house accounting department. Our outsourced services are available at a fraction of in-house accounting costs, giving new founders more room to invest in hiring, product development, and business growth.
Our Expert Insight
One issue we often see in startup accounting is that founders review their numbers only when they need to file taxes or share reports with an investor. By then, a problem that began months ago may be harder to fix.
For example, a startup may show higher sales each month but still face a cash shortage. A review may show that clients take 60 days to pay, while vendors expect payment within 15 days. The business is earning revenue, but cash is going out well before it comes in.
A monthly review of receivables, payables, bank balances, and cash flow can bring this gap to light. The founder can then follow up on late invoices, review payment terms, or plan cash needs before bills fall due.
This is why good accounting is not just about keeping records. It is about checking what the numbers mean and acting on them while there is still time to make a change.
Key Takeaways
- A strong financial base helps startups track money, manage costs, and plan for growth.
- Accountants for startups help set up books, manage cash flow, handle payroll, and prepare financial reports.
- Clean records make tax work easier and help when seeking loans or investment.
- Founders should avoid mixing personal and business funds, skipping bank checks, and delaying bookkeeping.
- Monthly reviews help spot cash flow gaps and cost issues before they grow.
- The right startup accounting firm can provide skilled support as a business grows, without the cost of a full in-house team.
FAQs
Look for an accountant with experience working with startups, knowledge of your industry, and a clear understanding of business taxes and financial reporting. Ask about their services, reporting schedule, and how they check the accuracy of your books.
Cash-basis accounting records income and expenses when money is received or paid. Accrual accounting records them when income is earned or expenses are incurred. The right choice depends on your business structure, tax requirements, and reporting needs.
Founder investments should be recorded as owner contributions or equity, depending on the business structure. Loans should be listed as liabilities, with principal and interest recorded separately. This keeps business income and funding records clear.
Investors may ask for profit and loss statements, balance sheets, cash flow statements, financial forecasts, and revenue reports. They may also review tax returns, funding records, and details of existing debt before making an investment decision.
Review available cash, expected revenue, salary, payroll taxes, benefits, and other hiring costs. Also, estimate how long the business can cover these costs if sales fall short. This helps founders make hiring decisions without putting pressure on daily cash flow.
optional anymore
on running the business