A certified industrial accountant examines how raw material prices, labor costs, machine output, and factory overhead affect a manufacturer’s profit. When a batch costs more than planned, the business needs to know whether the cause is waste, higher purchase prices, excess labor hours, or low production output.
An Industrial cost accounting specialist connects factory records with financial results to identify these gaps. For small manufacturers, this analysis gives a sound basis for pricing, stock control, production planning, and cash flow decisions.
What You Will Learn From This Blog
- The duties of a certified industrial accountant in a manufacturing business.
- The formulas used to measure manufacturing KPIs.
- How to calculate material, labor, and overhead cost variances.
- How an Industrial cost accounting specialist reviews product costs and cash flow.
- Which financial reports and cash controls manufacturers should maintain.
Role and Responsibilities of a Certified Industrial Accountant in a Manufacturing Business
A certified industrial accountant links production activity with financial results and checks whether costs remain within approved limits.
Product Costing and Budget Control
The accountant records direct materials, labor, and factory overhead for each product or batch. An Industrial cost accounting professional compares actual costs with budgeted figures and investigates significant gaps.
Inventory Valuation and Reconciliation
Stock records must cover raw materials, work in progress, and finished goods. A certified industrial accountant checks physical counts, investigates shortages, and reviews the value of damaged or obsolete stock.
Production Performance Analysis
The accountant tracks output, machine downtime, scrap, and labor efficiency. These measures show whether poor production performance is raising the cost of each finished unit.
Financial Reporting and Compliance
Monthly accounts must reflect sales, production costs, inventory, and cash balances. A certified industrial accountant checks the records against the reporting and tax rules that apply to the business.
optional anymore
on running the business
How an Industrial Cost Accounting Specialist Differs From a General Accountant
A general accountant manages financial records and reports, while an Industrial Cost Accounting Specialist focuses on manufacturing costs, production efficiency, and product profitability.
Basis | General Accountant | Industrial Cost Accounting Specialist |
Main Responsibilities | Maintains accounts, prepares financial statements, and records business transactions. | Tracks production costs and analyses factory performance. |
Cost Calculation | Records business expenses and supplier payments. | Calculates product costs using materials, labor, and factory overhead. |
Inventory Management | Reconciles stock accounts and reports inventory value. | Tracks raw materials, work in progress, finished goods, and scrap. |
Production Analysis | Reviews overall business expenses and financial results. | Measures material usage, machine downtime, and labor efficiency. |
Cost Variance Analysis | Compares actual expenses with budgeted amounts. | Identifies material, labor, and overhead cost variances. |
Pricing Decisions | Provides revenue and expense data for pricing reviews. | Calculates unit costs and product margins for pricing decisions. |
Financial Reports | Prepares financial statements and tax records. | Prepares production cost sheets and manufacturing KPI reports. |
Practical Example | Records the factory’s monthly electricity bill of ₹2,40,000. | Compares electricity costs with machine hours and production output to identify cost increases. |
Both roles contribute to financial control, but an Industrial cost accounting specialist provides detailed cost data for manufacturing and production decisions.
Essential Manufacturing KPIs Every Small Business Should Track
A certified industrial accountant reviews KPIs to connect production performance with profit and working capital.
Gross Margin and Contribution Margin Per Product
Gross Margin = (Net Sales − Cost of Goods Sold) ÷ Net Sales × 100
Contribution Per Unit = Selling Price − Variable Cost Per Unit
A product sold for ₹500 with a cost of goods sold of ₹350 has a gross margin of 30%. Contribution margin shows how much remains after variable costs to cover fixed costs and profit.
Cost Per Unit and Cost of Goods Manufactured
Cost Per Unit = Total Production Cost ÷ Units Produced
COGM = Opening Work in Progress + Manufacturing Costs − Closing Work in Progress
If a factory spends ₹6,00,000 to produce 4,000 units, its average production cost is ₹150 per unit. An Industrial cost accounting specialist compares this result with the budget to identify cost increases.
Inventory Turnover and Days Inventory Outstanding
Inventory Turnover = Cost of Goods Sold ÷ Average Inventory
DIO = Average Inventory ÷ Cost of Goods Sold × Days in Period
Annual cost of goods sold of ₹36 lakh and average inventory of ₹6 lakh give six inventory turns per year, or about 61 days of inventory using a 365-day year. A certified industrial accountant reviews this result against demand and supplier lead times.
OEE (Overall Equipment Effectiveness)
OEE = Availability × Performance × Quality
With 90% availability, 85% performance, and 98% quality, OEE is about 75%. An Industrial cost accounting professional reviews downtime, slow cycles, and defects to identify lost output.
Scrap and Rework Rate
Scrap Rate = Scrapped Units ÷ Total Units Produced × 100
If 60 of 2,000 units are scrapped, the scrap rate is 3%. A certified industrial accountant measures the related material and labor costs to show the financial effect of production waste.
On-Time Delivery and Cash Conversion Cycle
On-Time Delivery = Orders Delivered on Time ÷ Orders Due × 100
Cash Conversion Cycle = DIO + DSO − DPO
These measures show whether orders reach customers on time and how long cash remains tied up in stock and unpaid invoices.
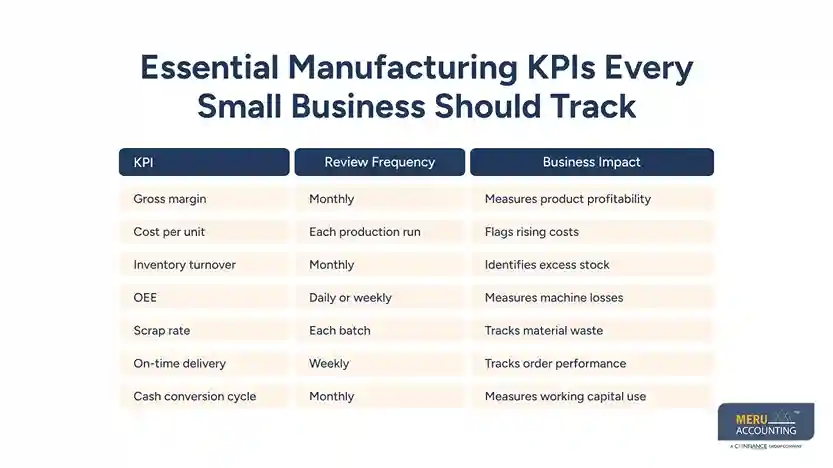
Manufacturing KPI Benchmark Table
KPI | Review Frequency | Business Impact |
Gross margin | Monthly | Measures product profitability |
Cost per unit | Each production run | Flags rising costs |
Inventory turnover | Monthly | Identifies excess stock |
OEE | Daily or weekly | Measures machine losses |
Scrap rate | Each batch | Tracks material waste |
On-time delivery | Weekly | Tracks order performance |
Cash conversion cycle | Monthly | Measures working capital use |
Targets should reflect the product, production method, past results, and supplier lead times rather than a universal benchmark.
Cost Variance Analysis Explained
Cost variance analysis compares planned costs with actual spending. A certified industrial accountant separates price changes from resource waste so management can identify the cause of overspending.
Standard Costing vs. Actual Costing
Standard costing sets expected costs before production begins, while actual costing records the costs incurred. An Industrial cost accounting specialist compares the two to find differences in material, labor, and overhead.
Material Price and Usage Variance
Price Variance = Actual Quantity × (Actual Price − Standard Price)
Usage Variance = Standard Price × (Actual Quantity − Standard Quantity Allowed)
These calculations distinguish higher purchase prices from excess material use.
Labor Rate and Efficiency Variance
Rate Variance = Actual Hours × (Actual Rate − Standard Rate)
Efficiency Variance = Standard Rate × (Actual Hours − Standard Hours Allowed)
A certified industrial accountant checks overtime, machine delays, and production records before assigning a cause to labor variances.
Overhead Spending and Volume Variance
Spending variance compares actual overhead with the budget allowed for the actual activity level. Volume variance measures the effect of producing more or fewer units than planned under the selected costing method.
Worked Example With Actual Figures
A factory plans to use 200 kg of material at ₹50 per kg, giving a standard cost of ₹10,000. Actual use is 210 kg at ₹55 per kg, bringing the cost to ₹11,550.
- Price variance: 210 × ₹5 = ₹1,050 unfavorable.
- Usage variance: 10 × ₹50 = ₹500 unfavorable.
- Total material variance: ₹1,550 unfavorable.
An Industrial cost accounting specialist should check purchase invoices, material quality, and cutting waste before recommending changes.
Favorable and Unfavorable Variances
A favorable variance means actual costs are below plan; an unfavorable variance means they exceed plan. A certified industrial accountant checks the reason before recommending action because cheaper material can increase defects, while extra labor may result from a profitable rush order.
How Industrial Cost Accounting Protects Your Cash Flow
An Industrial cost accounting professional uses cost and stock records to identify spending that ties up cash without earning a suitable return.
Accurate Product Costing and Pricing Decisions
Includes material, labor, and factory overhead in product costs. A certified industrial accountant compares the result with selling prices, discounts, and delivery costs before reviewing low-margin orders.
Activity-Based Costing for Overhead Allocation
Activity-based costing assigns overhead based on activities such as machine setups and quality checks. This gives an Industrial cost accounting professional a clearer view of products that consume different levels of factory resources.
Identifying Unprofitable Products and Customers
Review product margins after returns, special packaging, and delivery costs. A certified industrial accountant can identify products or customer orders that generate sales but contribute little profit.
Budgeting and Forecasting Production Costs
Build budgets from expected orders, material prices, labor needs, and machine capacity. An Industrial cost accounting specialist updates forecasts when demand or supplier costs change.
Financial Reporting for Manufacturers
A certified industrial accountant checks that production records flow correctly into financial statements and management reports.
Core Financial Statements
The income statement reports revenue and expenses, the balance sheet shows assets and liabilities, and the cash flow statement records operating, investing, and financing cash movements.
Cost of Goods Manufactured Schedule
This schedule combines direct materials used, direct labor, and factory overhead, adjusted for opening and closing work in progress. A certified industrial accountant uses it to measure the cost of goods completed during the period.
Management Reports vs. Statutory Reporting
Management reports track product margins, scrap, and budget gaps. Statutory reports follow applicable reporting rules. Both need consistent source records, even though their purposes differ.
Inventory Valuation: FIFO and Weighted Average
FIFO assigns older eligible costs to goods sold first, while weighted average uses an average cost for similar items. The method affects reported stock and profit, subject to applicable accounting rules.
GAAP, IFRS, GST, and Tax Requirements
Manufacturers must follow the reporting framework and tax laws that apply to their location and business structure. An Industrial cost accounting professional should work with qualified tax professionals when requirements need specialist review.
Building a Monthly Reporting Dashboard
Track sales, gross margin, unit costs, inventory, scrap, overdue invoices, and cash forecasts. A certified industrial accountant should explain major changes and record the action required.
Practical Cash Flow Strategies for Small Manufacturers
Optimizing Inventory Levels
Set reorder points using demand, supplier lead times, and safety stock. Just-in-time buying can reduce storage costs, but critical materials may need extra stock to prevent production delays.
Negotiating Supplier Terms
Compare early-payment discounts with the cost of using cash sooner. Agree on terms that protect working capital while maintaining reliable supply.
Tightening Receivables and Invoicing
Issue accurate invoices promptly and follow up on overdue accounts. Resolve purchase order errors and billing disputes early to reduce payment delays.
Using a 13-Week Cash Flow Forecast
List opening cash, weekly receipts, supplier payments, payroll, taxes, loan payments, and other costs for 13 weeks. A certified industrial accountant can compare weekly cash flow forecasts with actual receipts and payments to identify potential cash shortages before bills fall due.
Using Variance Data to Adjust Buying and Pricing
Review repeated cost increases before changing prices or suppliers. An Industrial cost accounting specialist compares buying rates, waste, and production costs to identify actions that protect margins without reducing quality.
Why Meru Accounting Stands Out in Manufacturing Accounting
Meru Accounting provides manufacturing accounting services that give business owners a clear view of production costs, inventory value, and financial performance.
- Accurate Production Costing: Our cost accounting services track material, labor, and factory overhead expenses, giving a certified industrial accountant the figures needed to calculate product costs and profit margins
- Inventory Cost Control: Meru Accounting maintains records of raw materials, work in progress, and finished goods to help manufacturers monitor inventory value.
- Cost Variance Analysis: We compare actual production expenses with budgeted costs to identify overspending, material waste, and labor cost differences.
- Reliable Financial Reporting: Our financial reporting services provide income statements, balance sheets, and manufacturing cost reports for informed business decisions.
- Cash Flow Planning: Meru Accounting tracks customer receivables, supplier payments, and operating expenses to help manufacturers plan cash requirements.
- Profitability Analysis: We review product costs and margins to identify unprofitable products and opportunities to reduce production expenses.
Our Expert Perspective
A certified industrial accountant should not treat an unfavorable cost variance as a simple accounting error. For example, if material costs rise by 8% while production output remains unchanged, the review should compare supplier prices, material usage, and scrap levels before recommending a change.
An Industrial cost accounting specialist should also link these findings to product margins and cash flow. This approach gives management clear evidence for decisions about pricing, supplier terms, stock purchases, and production methods.
Key Takeaways
- Track material, labor, and overhead costs to measure product profitability.
- Review manufacturing KPIs to find waste, downtime, and excess stock.
- Separate material price variances from usage and labor variances.
- Maintain consistent inventory records and financial reports.
- Update cash forecasts weekly to prepare for upcoming payments.
FAQs
A certified industrial accountant tracks production costs, manufacturing KPIs, cost variances, inventory values, and financial reports to measure factory performance.
An industrial accountant should track gross margin, cost per unit, inventory turnover, OEE, scrap rate, on-time delivery, and the cash conversion cycle.
Cost variance analysis compares actual production costs with standard costs to identify differences in material prices, material usage, labor efficiency, and factory overhead.
An industrial cost accounting specialist identifies material waste, excess labor hours, machine downtime, and overhead costs that reduce manufacturing profit.
Manufacturing businesses need an income statement, balance sheet, cash flow statement, cost of goods manufactured schedule, and monthly production cost reports.
optional anymore
on running the business