A medical practice can have a full appointment schedule and still face cash flow problems. Insurance payments may take weeks to arrive, patient balances can remain unpaid, and costs like staff wages, medical supplies, and lab fees keep adding up. QuickBooks for healthcare can help medical practices keep track of these numbers and get a clearer view of their financial health.
With the right setup, QuickBooks can help clinics record patient service income, track expenses, manage payroll, and review monthly reports. However, healthcare accounting also involves insurance reimbursements, claim adjustments, and patient billing, which may require separate tools and careful recordkeeping.
In this blog, we’ll look at how medical practices can use QuickBooks to manage their finances, which features are worth using, and what to know about HIPAA, bookkeeping, and accounting support.
What You Will Learn From This Blog
- How QuickBooks works for medical offices, clinics, and other healthcare businesses.
- Which QuickBooks features can help track income, costs, payroll, and reports.
- How to record patient payments and insurance reimbursements.
- Key points to consider for healthcare bookkeeping and data safety.
- When a medical practice may need expert QuickBooks accounting support.
What Is QuickBooks for Healthcare, and How Does It Work?
QuickBooks is an accounting tool that helps businesses record income, track costs, manage bills, and review financial results. It is not a medical billing or practice management system. Still, healthcare providers can use it to manage the financial side of their work.
QuickBooks for healthcare refers to using QuickBooks to track the money a medical practice earns and spends. A clinic may use it to record payments, pay vendors, track staff costs, and review monthly income and expenses. It can also help the owner see how much cash is on hand and which costs are rising.
For example, a dental office may use a practice management system to book visits and send claims. Once payments reach the bank, the finance team can record and match them in QuickBooks. This helps keep the books in line with the money the office has earned and received.
QuickBooks Online may suit practices that want cloud access and bank feeds. QuickBooks Desktop may fit firms that rely on a local setup or certain desktop tools. The right choice depends on the practice’s size, work flow, reporting needs, and other tools.
Key Features of QuickBooks for Healthcare Practices
QuickBooks offers a set of tools that can help medical offices keep their books in order. The value of each feature depends on how the practice bills patients, pays staff, and tracks costs.
1. Income and Expense Tracking
A medical practice may earn money from patient visits, care plans, tests, and other services. It may also spend money on rent, supplies, lab fees, software, and utilities. QuickBooks lets the team record these items under set income and expense accounts.
This helps owners see where money comes from and where it goes. It also makes it easier to spot high costs and review changes from one month to the next.
2. Payroll and Staff Cost Tracking
Staff costs can take up a large share of a clinic’s budget. QuickBooks can help track wages, payroll costs, and related expenses. Depending on the plan and setup, payroll may be handled through an added QuickBooks Payroll service.
A clear payroll record helps owners review labor costs, plan staff needs, and keep pay records in order. Practices should also check that payroll tax filings and state rules are met.
3. Accounts Payable and Receivable
Medical offices often pay vendors for supplies, lab work, rent, and other needs. QuickBooks can track bills, due dates, and vendor payments. This helps the team avoid late fees and plan cash needs.
It can also track amounts due from customers or other payers. However, detailed patient billing and insurance claim work often need a separate medical billing system.
4. Bank and Credit Card Reconciliation
Bank feeds can bring account activity into QuickBooks. The bookkeeper can then match each item to the right entry in the books.
Monthly bank and card checks help find missing entries, double entries, and wrong amounts. This step is key to keeping the books in line with bank records.
5. Financial Reports and Cash Flow Review
QuickBooks can create reports such as the profit and loss statement, balance sheet, and cash flow report. These help owners review income, costs, assets, debts, and cash flow.
A monthly review can show if supply costs have gone up, if payroll is too high, or if the practice has enough cash to meet its bills.
How to Manage Healthcare Finances With QuickBooks
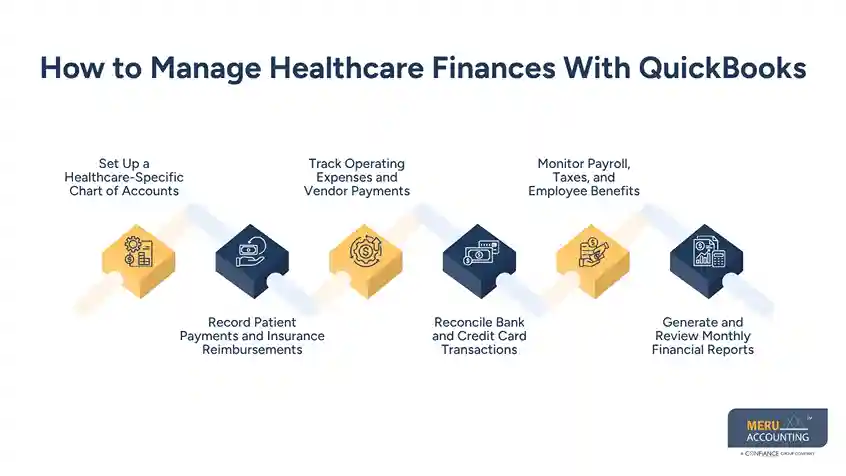
Using QuickBooks well requires more than recording payments and bills. Medical practices need a clear process for tracking income, checking costs, and keeping records up to date. Here are some steps that can help.
1. Set Up a Healthcare-Specific Chart of Accounts
Start by setting up a chart of accounts that fits the practice. This is a list of accounts used to group income, costs, assets, and debts.
For example, a medical office may use accounts for patient service income, insurance payments, medical supplies, rent, staff wages, lab fees, and equipment. A clear setup makes it easier to review each part of the business.
Avoid placing all costs under one general expense account. Separate records help owners see which areas use the most money.
2. Record Patient Payments and Insurance Reimbursements
Medical practices may receive payments from patients, insurers, and other payers. Each source should be recorded in the right way.
For example, a clinic may bill an insurer for $500 and later receive $350 after a claim review. The rest may be a patient balance, a contract adjustment, or an amount still under review. The practice should not record the full claim as cash received.
Use the medical billing system to track claim details and payment status. Then record the right amounts in QuickBooks and match deposits to the related entries. This helps prevent errors when one bank deposit covers many claims.
3. Track Operating Expenses and Vendor Payments
Record bills for medical supplies, rent, lab work, utilities, software, and other costs as they arise. Add the vendor name, bill date, due date, and expense type.
This gives the team a clear view of what the practice owes and when each bill is due. It also helps owners plan cash needs and avoid late fees.
Keep receipts and invoices with the related entries. These records can help support tax filings and make it easier to answer questions during a review.
4. Reconcile Bank and Credit Card Transactions
At the end of each month, compare the bank and card statements with the records in QuickBooks. Check that each payment, deposit, fee, and transfer is recorded once.
Pay close attention to grouped deposits from payment processors. A bank deposit may be lower than the total patient payments because the processor has taken its fees. Record the gross payments and fees in the right accounts so the books show the full picture.
5. Monitor Payroll, Taxes, and Employee Benefits
Review payroll costs, tax payments, and staff benefits each month. Check that wages match payroll reports and that tax amounts are recorded in the right accounts.
Medical practices may have doctors, nurses, front desk staff, and part-time workers. Separate cost records can help owners review staffing costs and plan their budget.
6. Generate and Review Monthly Financial Reports
Run a profit and loss statement, balance sheet, and cash flow report each month. Compare the results with the prior month and the same period last year.
Look for changes in income, supply costs, wages, and unpaid bills. If costs rise but income stays flat, the owner can look into the cause and act early.
QuickBooks Healthcare Accounting: Important Considerations for Medical Practices
QuickBooks healthcare accounting needs care because medical practices deal with more than routine sales and costs. They must also handle payer rules, patient balances, and private data.
Here are some key points to keep in mind.
1. Separate Clinical Revenue From Other Income
A practice may earn money from office visits, tests, procedures, and other services. It may also earn income from product sales or other sources.
Use clear income accounts for each main source. This helps owners see which services bring in the most money and compare income over time.
2. Plan for Insurance Claim and Payment Delays
An insurer may take weeks to review and pay a claim. A claim may also be denied, reduced, or sent back for more details.
Do not treat every claim as cash in the bank. Use the billing system to track claim status and record payments only when they are due or received, based on the practice’s accounting method. Review unpaid amounts on a regular basis.
3. Track Patient Balances With Care
Patient balances can arise from co-pays, deductibles, or services not paid by an insurer. Keep these records in a secure billing system and use the right summary entries in QuickBooks.
This helps the practice review what it is owed without placing more patient data in its accounting file than needed.
4. Keep Tax and Expense Records Up to Date
Save records for medical supplies, rent, staff pay, equipment, insurance, and other business costs. Check that each cost is placed in the right account.
Medical equipment may need to be treated as a fixed asset rather than a routine expense. Its cost may be spread over time through depreciation, based on tax rules and the type of asset. A tax professional can help decide how each item should be handled.
5. Review User Access and Data Security
Limit access to financial records based on each staff member’s role. Use strong passwords, multi-factor login where available, and regular access reviews.
Also, avoid placing patient names, diagnoses, or other protected health details in QuickBooks notes, invoice fields, or memos. Keep patient-level data in a system built for medical billing and care records.
optional anymore
on running the business
Is QuickBooks HIPAA Compliant? What Healthcare Providers Should Know
QuickBooks should not be treated as a HIPAA-compliant medical record or patient billing system by default. HIPAA rules apply to covered entities and business associates that handle protected health information (PHI). A medical practice must review the tools it uses and how it shares data.
Before using QuickBooks, healthcare providers should:
- Limit PHI: Do not enter patient names, diagnoses, or care details unless the use has been reviewed and approved.
- Check vendor terms: Ask the vendor whether the specific product and service are covered by a Business Associate Agreement (BAA), where one is required.
- Set user access: Give staff access only to the records they need for their jobs.
- Use safe data practices: Protect logins, review access, and keep systems up to date.
- Review connected apps: Check how billing, payment, and accounting tools share data.
A BAA alone does not make a practice HIPAA compliant. The practice must also use the right safeguards, staff rules, and risk checks. If QuickBooks is used only for general financial records with no PHI, the risk may be lower, but the full data flow still needs review.
QuickBooks Accounting Services for Healthcare Practices by Meru Accounting
Healthcare accounting requires close attention to insurance payments, patient balances, payroll, and operating costs. A small error in payment records or expense entries can affect your monthly reports and cash flow. At Meru Accounting, we help healthcare practices keep their QuickBooks records accurate and organized with accounting support that fits their existing workflows.
Our QuickBooks accounting services include:
- Bookkeeping: Record income, expenses, bills, and daily transactions.
- Payment Reconciliation: Match bank deposits with patient and insurance payment records.
- Accounts Payable and Receivable: Track vendor bills, due payments, and outstanding balances.
- Payroll Accounting: Maintain employee wage and payroll expense records.
- Financial Reporting: Prepare monthly profit and loss statements, balance sheets, and cash flow reports.
- QuickBooks Cleanup: Fix duplicate entries, incorrect account classifications, and unreconciled transactions.
Our team brings multi-industry accounting experience and works with QuickBooks Online and Desktop. We also adapt to your existing accounting setup instead of asking you to change your workflow. Whether you need regular bookkeeping or help cleaning up your QuickBooks records, we provide support based on your practice’s needs.
Our Expert Insight
One thing medical practice owners should watch is the difference between revenue growth and actual profitability. A clinic may see more patients and report higher monthly revenue, but rising staff costs, lab fees, medical supplies, and equipment expenses can reduce its profit.
For example, if a practice’s revenue grows by 15% but its operating costs rise by 22%, higher sales may not lead to better financial results. This is why we recommend reviewing monthly expenses alongside revenue, rather than judging business performance by collections alone.
A monthly review of profit and loss reports, expense trends, and cash flow can help practice owners spot rising costs, assess service profitability, and make better decisions about staffing and spending.
Key Takeaways
- QuickBooks for healthcare can help medical practices track income, expenses, payroll, bills, and financial reports.
- A clear chart of accounts makes it easier to review medical practice costs and income.
- Patient billing and insurance claim tracking may need a separate medical billing system.
- Monthly bank reconciliation helps find missing, duplicate, or incorrect entries.
- QuickBooks should not be treated as a HIPAA-compliant patient record system by default.
- A skilled accountant can help keep books accurate and support better financial decisions.
FAQs
Yes. QuickBooks can track income and expenses by provider or office using classes or locations, depending on the plan and setup.
Record contractual adjustments separately from operating expenses. Use the insurer’s remittance advice to support each adjustment.
Yes. Record qualifying equipment as a fixed asset and apply the appropriate depreciation method based on tax rules.
QuickBooks Online suits practices that need cloud access, while Desktop may fit those with specific local workflows or reporting needs.
Review the profit and loss statement, balance sheet, cash flow statement, and accounts receivable aging report to monitor costs, cash, and unpaid balances.
optional anymore
on running the business