QuickBooks for real estate agents can give you a clear view of your cash, fees, and deal income. Real estate work has many moving parts. One sale may bring a large fee, while part of that fee goes to a broker, team, or referral partner.
The hard part is not just adding a bank feed. You need to know what each payment means. A clean set of books can show gross commission, broker fees, referral fees, ad costs, travel costs, and the cash left for your firm.
QuickBooks for real estate agents works best when the file is set up around the way your deals are paid. A bank deposit alone may not tell the full story. The commission statement, closing data, and fee details may also need review.
For agents who want clear reports, QuickBooks real estate bookkeeping can turn a pile of deal data into a useful monthly view. The goal is simple: know what you earned, what you paid, and what you kept.
What You Will Learn From This Blog
- Tracking commissions and deal income with QuickBooks for real estate agents.
- Setting up clear accounts for brokerage fees and broker splits.
- Recording referral income and referral fees paid to other agents.
- Splitting commission payments into the correct income and fee accounts in QuickBooks for real estate agents.
- Categorizing common expenses for real estate agents.
- Avoiding common errors in QuickBooks real estate bookkeeping.
- Keeping financial records organized for tax review.
- Managing ongoing real estate bookkeeping with Meru Accounting.
How QuickBooks for Real Estate Agents Works
Build A Real Estate Chart Of Accounts
A clear chart of accounts is the base of QuickBooks for real estate agents. Use simple names for income, broker fees, referral fees, ads, travel, dues, and other costs.
Do not make too many small accounts. Use names that tell you what each cost means when you view a profit and loss report.
Track Gross Commission Income
A deal may show a gross commission before the broker takes its share. Your books should show the right income and fee amounts based on your deal terms and tax setup.
For example, a $12,000 commission may lead to a $4,000 broker split and a $8,000 net payment. The books should not lose sight of the full deal value.
Match Bank Deposits With Deal Records
Bank feeds show cash that hit your account. They do not always show why the cash was paid or which fees were taken first.
Match each deposit with a commission statement, closing record, or other source record. That step gives QuickBooks real estate bookkeeping a much stronger base.
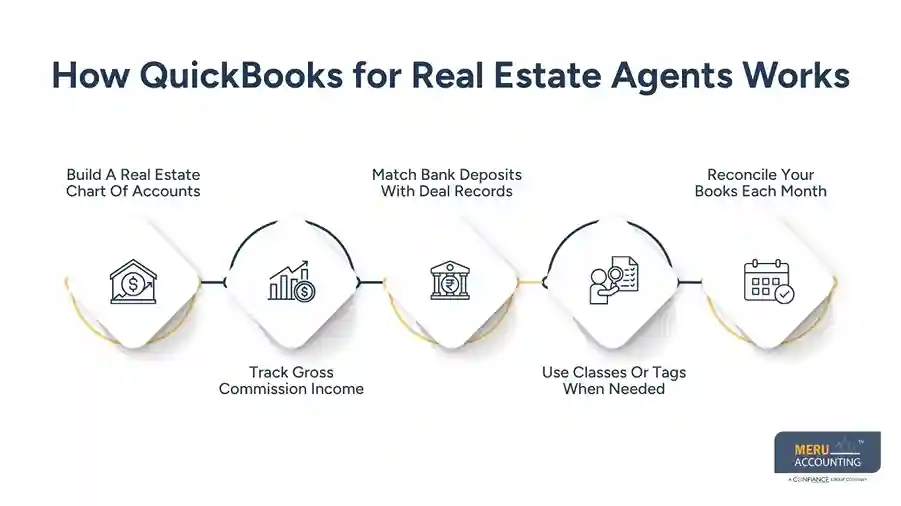
Use Classes Or Tags When Needed
Agents with more than one team, area, or line of work may need more detail. Classes or other tracking tools can show where income and costs came from.
QuickBooks for real estate agents can make separate tracking easier when you need to compare buyer deals, seller deals, and referral work.
Reconcile Your Books Each Month
A monthly bank check can find missing, wrong, or duplicate entries before they grow into a large clean-up job. It also gives you a better month-end report.
Make bank and card checks part of your normal QuickBooks real estate bookkeeping work rather than a task saved for tax time.
optional anymore
on running the business
How To Track Brokerage Fees In QuickBooks
Create A Broker Fee Account
Set up a clear account for fees paid to your broker. Keep broker splits apart from costs such as ads, office rent, software, or travel.
Separate accounts make it easier to see how much of your sales income goes to the broker over a month or year.
Record The Deal Before The Net Deposit
Suppose your gross commission is $10,000. Your broker keeps $3,000, and $7,000 reaches your bank.
QuickBooks for real estate agents should be set up to show the right gross and fee flow rather than treating the $7,000 bank deposit as the only part of the deal.
Split Fees By Type
One closing may have a broker split, desk fee, tech fee, transaction fee, and referral fee. With QuickBooks for real estate agents, avoid putting every fee into one broad cost account when you need to review each type.
A split entry gives you a better view of the true cost of each deal.
Keep The Commission Statement
Keep the statement that shows the gross fee, broker share, other fees, and net payment. Use that record when checking the QuickBooks entry.
The bank feed confirms the cash. The statement can give the detail behind that cash.
Check The Numbers After Closing
Regular reviews are an important part of using QuickBooks for real estate agents accurately after each closing or at month-end. Compare the deal record, commission statement, and bank entry.
That small step can catch a missed fee before the books are used for tax work or business planning.
How To Record Real Estate Referral Fees
Track Referral Income Separately
If you earn money for sending a client to another agent or firm, consider a separate income account for referral income. It keeps sales commissions and referral income easy to tell apart.
Separate income lines also give you a better view of which part of your business brings in cash.
Record Referral Fees You Pay
When you pay another agent or firm for a referral, use a suitable referral fee expense account. Keep the related agreement or invoice with the entry.
The right tax and reporting treatment can vary, so ask your tax adviser when the payment has special rules.
Link Each Referral To A Deal
With QuickBooks for real estate agents, add a client, deal, or property note when your setup allows it. That detail makes QuickBooks real estate bookkeeping easier to review later.
For example, a $1,500 referral fee should be easy to link to the deal that caused the payment.
Check Referral Payment Dates
The date you agree to a referral fee may not be the date you pay it. Keep both dates where they matter to your records.
Your tax method and deal terms can affect when an amount should be recorded. Ask a tax pro when the timing is not clear.
Keep Proof Of Payment
When using QuickBooks for real estate agents, keep the bill, referral form, agreement, and payment proof with your records. A clear paper trail makes it easier to answer questions later.
Accurate records also make the year-end review faster when several referral payments took place.
How To Categorize Real Estate Agent Expenses
Marketing And Lead Costs
Track ad spend, signs, mail, photos, online leads, and other marketing costs in suitable accounts. Keep business costs apart from personal spending.
A clean view of marketing costs can also show how much you spend to win new work.
MLS And Association Fees
MLS dues and trade group fees can be tracked in their own account. Separate them from ads and office costs when those numbers matter to your review.
Clear names make monthly reports much easier to read.
Travel And Car Costs
Real estate agents using QuickBooks for real estate agents can organize costs related to showings, listing sites, meetings, and other business travel. Keep a record of business trips and the cost tied to them.
For vehicle costs, keep the mileage and other records your tax adviser says you need.
Client And Closing Costs
Client gifts, photos, staging, open-house costs, and similar items should be reviewed and placed in the right accounts.
Do not assume every cost tied to a client has the same tax treatment. Ask a tax pro when a cost is unclear.
Software And Office Costs
QuickBooks for real estate agents can help organize CRM tools, accounting software, phone bills, office items, and other business costs into suitable accounts.
Using the same category each month keeps QuickBooks real estate bookkeeping clean and makes trend checks easier.
Common QuickBooks Bookkeeping Mistakes Real Estate Agents Make
Recording Only The Bank Deposit
A common error is to record only the cash that reaches the bank. That can hide the gross commission and the fees taken from it.
QuickBooks for real estate agents should reflect the full deal flow when your accounting and tax setup calls for gross income and separate fees.
Mixing Personal And Business Costs
Personal charges can make business reports hard to read. They can also create extra work when books are reviewed.
Use separate bank and card accounts for business use where possible.
Using One Fee Account
Putting broker splits, referral costs, tech fees, and office fees into one account hides useful detail.
Separate fee types when the business needs that level of review.
Skipping Monthly Reconciliation
Books can look fine while a duplicate or missing entry sits in the bank feed. Monthly checks keep QuickBooks for real estate agents’ records closer to the actual bank activity.
Make reconciliation a set part of your monthly QuickBooks real estate bookkeeping routine.
Trusting Every Bank Feed Match
Bank feeds can save time, but each match still needs a review. A transfer is not an expense, and a loan payment is not the same as a normal business cost.
Review unusual entries before you approve them.
Tips To Improve QuickBooks Real Estate Bookkeeping In 2026
Review Every Closing
Make a closing check part of your process. Review the gross commission, broker split, referral fee, other deductions, and net payment.
A set check can reduce the chance of missing a fee.
Use Bank Rules With Care
Bank rules can save time for repeat costs. Use them for clear and stable patterns, such as a known software charge.
Review the rules from time to time. A rule that once worked may later send a new charge to the wrong account.
Track Income By Source
Keep sales commissions, referral income, and other income types apart when they are a real part of your business.
That gives QuickBooks for real estate agents a better income view and can show which work brings the most cash.
Review Profit Each Month
Look at income, broker fees, referral costs, marketing, travel, and other costs each month. Do not focus only on the bank balance.
A cash balance can look strong while high deal costs are cutting your true profit.
Keep A Monthly Close List
Use the same close steps each month: check bank feeds, match deal records, review fees, reconcile accounts, and review reports.
A fixed list makes QuickBooks real estate bookkeeping more consistent and reduces the chance that a key task gets missed.
How Meru Accounting Handles Real Estate Bookkeeping
Deal-Level Record Review
Meru Accounting can review real estate transactions at the deal level instead of looking only at the bank balance. We can check commission records, broker deductions, referral amounts, and related entries for consistency.
Income And Fee Mapping
Our team can structure QuickBooks for real estate agents’ accounts to map different income and fee types correctly. That gives agents a clearer way to see where commission revenue comes from and where deal costs are going.
Support For Growing Agents
As deal volume rises, bookkeeping can become harder to manage. Meru Accounting can take care of recurring bookkeeping tasks so agents can spend more time on clients, listings, and closing new deals.
Records Ready For Review
We can organize transaction records so important entries are easier to find during monthly reviews. Clear records can also make communication with a CPA or tax preparer easier when tax work begins.
Ongoing Bookkeeping Care
Meru Accounting can provide recurring bookkeeping rather than only fixing old records. Regular checks can keep income, fees, expenses, and account balances up to date throughout the year.
Our Expert Insight
QuickBooks for real estate agents should show more than the cash received from a deal; agents should review commission income against broker splits, referral fees, marketing costs, and other deal expenses to understand the actual profit.
Keeping the same record method for every closing, referral, and fee payment makes reviews easier, while checking unusual charges before posting can prevent wrong categories. Regularly comparing fees with related revenue can also show when deal costs are rising and affecting profit.
QuickBooks real estate bookkeeping should therefore be treated as an ongoing review process, not simple data entry, so your records give a clear view of income, costs, cash flow, and profit.
Key Takeaways
- QuickBooks for real estate agents can provide a clear view of deal income and related fee costs.
- Gross commissions and brokerage fees should be recorded based on the business’s accounting setup.
- Referral income should be kept separate from regular sales commission income.
- Record referral payments with clear details and supporting records.
- QuickBooks for real estate agents can make each closing easier to review for missing, duplicate, or incorrect entries.
- Bank and credit card accounts should be reconciled every month.
- Records for commissions, fees, and expenses should be kept for future review.
- QuickBooks real estate bookkeeping should be maintained as a regular monthly process.
FAQs
Real estate agents can track brokerage fees in QuickBooks by recording commission income and broker deductions in clear, separate accounts.
Record a referral fee paid as a business expense in a suitable referral fee account and keep the related agreement, invoice, and payment record.
Record the commission based on the gross income and related broker deductions shown in your commission or closing statement.
The best approach when using QuickBooks for real estate agents is to use clear income and expense accounts, match each deposit to its deal record, and review brokerage and referral fees each month.
Yes, QuickBooks for real estate agents can track brokerage splits and referral fees when separate accounts and consistent transaction records are used.
optional anymore
on running the business