You sold an investment property, found a new one, and plan to roll the proceeds into the next deal. Sounds simple, right? Not quite. Real estate investor bookkeeping gets more complex when a 1031 exchange is involved. You now have sale proceeds, a qualified intermediary, closing costs, debt, and a new property to account for—all while keeping the old property’s financial history intact.
The challenge is making sure each part of the exchange has a clear paper trail. Your books should show what happened to the sale proceeds, how much was used for the replacement property, what costs were paid, and how the new property was added to your records. Good bookkeeping for real estate investors also gives your CPA or tax advisor cleaner records to work with when reviewing the exchange.
In this blog, we’ll walk through the 1031 exchange bookkeeping process step by step, including what to record, which documents to keep, and where investors often run into problems.
What You Will Learn From This Blog
In this blog, you will learn:
- What 1031 exchange bookkeeping means
- How a deferred 1031 exchange works
- How to record the main steps in your books
- What funds, costs, debt, and basis to track
- Which records should be kept
- Common bookkeeping issues to avoid
- How a bookkeeper can work with your CPA and qualified intermediary
What Is 1031 Exchange Bookkeeping?
1031 exchange bookkeeping is the process of tracking the financial records tied to a like-kind exchange. It covers the sale of the old property, exchange funds, closing costs, purchase of the new property, debt, and other related items.
Section 1031 generally applies to real property held for investment or business use. The property being sold and the replacement property must meet the rules for like-kind treatment.
Bookkeeping does not decide if an exchange qualifies. That is a tax and legal matter. Instead, the books should give your tax team the facts they need.
For example, your records should make it easy to see:
- The adjusted basis of the old property
- The sale price and related costs
- Funds sent to the qualified intermediary
- Costs paid as part of the exchange
- Cash added to buy the new property
- New debt and loan costs
- The cost and basis of the new property
How Does a 1031 Exchange Work?
A deferred 1031 exchange does not mean you simply sell one property and later buy another with the cash. There are strict rules around the flow of funds and the timing of the deal.
In a typical deferred exchange, the investor sells the property being given up. A qualified intermediary can hold the exchange funds so the investor does not take actual or constructive receipt of the proceeds.
The investor then has:
- 45 days to identify replacement property in writing.
- 180 days to receive the replacement property, or by the due date of the tax return, including extensions, if that date comes first.
The replacement property must meet the applicable Section 1031 rules. Real property can generally be like-kind even when the properties differ in type, grade, or quality, as long as the other requirements are met.
From a bookkeeping view, this creates three key stages:
Old property → Exchange funds → New property
Each stage needs its own clear records.
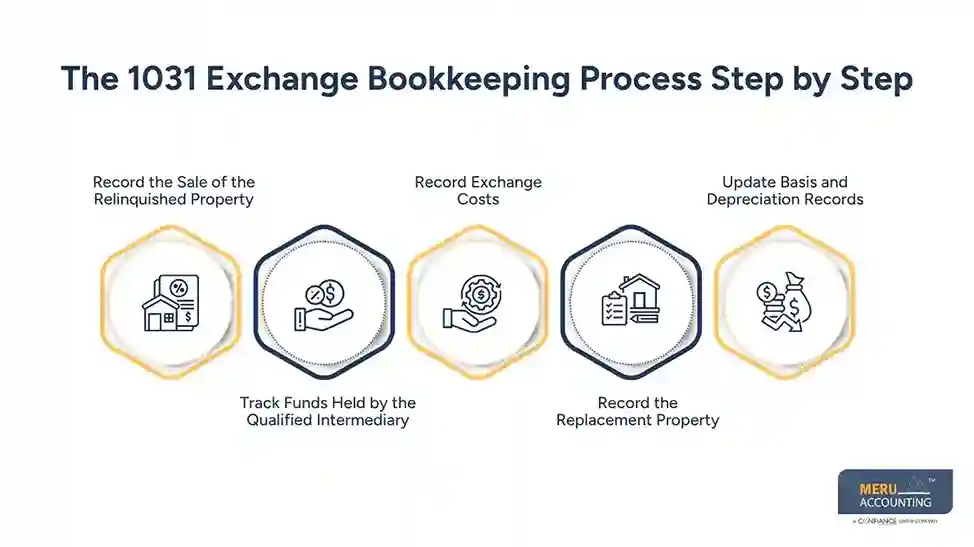
The 1031 Exchange Bookkeeping Process Step by Step
Record the Sale of the Relinquished Property
Start with the property being sold.
Your books should show the sale price, closing costs, loan payoff, and other related amounts. You also need the property’s current book value and depreciation records.
Do not treat the full sale proceeds as normal income. A 1031 exchange can defer gain when the rules are met. If cash or other non-like-kind property is received, some gain may be recognized.
Your bookkeeping should therefore preserve the full transaction trail instead of simply posting the net cash from closing.
Track Funds Held by the Qualified Intermediary
After the sale, exchange funds may be held by the qualified intermediary.
This money should be tracked in a way that clearly separates it from your normal operating cash.
The goal is to show:
Sale proceeds → funds held by QI → funds used for replacement property
Your records should match the settlement statement and the QI’s records.
Record Exchange Costs
A 1031 exchange may include several costs, such as closing fees, title charges, legal fees, recording fees, and other transaction costs.
Do not place every closing cost into one generic expense account without review. Some costs may affect the exchange calculation or property basis rather than being treated as a normal operating expense.
Your CPA should determine the tax treatment of each item.
optional anymore
on running the business
Record the Replacement Property
Once the replacement property is purchased, record the transaction in the correct property or entity books.
Track:
- Purchase price
- Closing costs
- New loan
- Cash added
- Exchange funds used
- Capital items
- Other acquisition costs
The new property’s tax basis is not always the same as its purchase price. The IRS states that the basis of property received in a like-kind exchange is generally tied to the basis of the property given up, with adjustments for money, other property, and recognized gain or loss.
That makes accurate old-property records very important.
Update Basis and Depreciation Records
After the exchange, your books should not simply start a brand-new property record based on the purchase price.
Your tax team will need to determine the proper basis of the replacement property.
Once that amount is known, update your depreciation schedule and asset records. Keep the old property’s history with the new property records so the basis trail is easy to follow.
This is one of the areas where real estate investor bookkeeping and tax work need to stay closely linked.
What Should Real Estate Investors Track During a 1031 Exchange?
Good bookkeeping for real estate investors should track more than just income and expenses.
During an exchange, pay close attention to:
Sale Proceeds
Track the gross sale amount and the net funds shown on the closing statement.
Adjusted Basis
Keep the old property’s purchase records, improvements, depreciation, and other basis details.
Exchange Funds
Track the amount transferred to the qualified intermediary and the amount later used for the replacement property.
Debt
Record the old loan payoff and new loan. Debt can affect the exchange calculation, so your tax advisor should review the numbers.
Cash Added
If you put more money into the replacement property, keep a clear record of the source and amount.
Closing Costs
Keep each major cost tied to the right property and transaction.
Capital Improvements
Track improvements separately from routine repairs and maintenance.
Depreciation
Keep the depreciation schedule for the old property and update records for the replacement property after the exchange.
What Records Should You Keep for a 1031 Exchange?
Strong records make the exchange easier to review and report.
Keep copies of:
- Purchase agreements
- Sale agreements
- Closing statements
- Settlement statements
- Qualified intermediary documents
- Bank statements
- Loan documents
- Mortgage payoff records
- Property improvement invoices
- Depreciation schedules
- Property tax records
- Legal and professional fee invoices
- Records of cash added to the deal
- Documents showing the identification of replacement property
The IRS uses Form 882 by similar exchanges, to report qualifying like-kind exchanges. The form also helps calculate recognized gain and the basis of like-kind property received.
Your bookkeeping records should support the numbers given to your tax professional for this filing.
Real Estate Investor Bookkeeping Services From Meru Accounting
A 1031 exchange can expose gaps in your books that may not be obvious during day-to-day property management. At Meru Accounting, we understand that real estate books need to do more than track rent and expenses. They need to show the full financial history of each property and support the records needed when a property is sold and replaced.
Our real estate investor bookkeeping services can include:
- Property-level bookkeeping: Separate income, expenses, assets, and liabilities for each property or entity.
- Transaction recording: Record property sales, purchases, loans, capital contributions, distributions, and other deal activity.
- Bank and account reconciliation: Match transactions to bank and financial records so your books stay accurate.
- Fixed asset tracking: Maintain property, improvement, and depreciation records for ongoing reporting.
- 1031 exchange support: Organize sale proceeds, exchange-related costs, replacement property transactions, and supporting documents for review by your tax professional.
- Financial reporting: Provide clear reports that help you see property performance, cash flow, and financial position.
With experience in bookkeeping for real estate investors, Meru Accounting focuses on keeping complex property records structured and easy to review. We work alongside your CPA or tax advisor, giving them reliable financial records while you stay focused on managing your investments and planning your next deal.
Our Expert Insight
One thing we see often is that investors focus on the exchange itself but overlook the entity structure behind the property. When properties are held through LLCs or other entities, the books need to match the legal owner and the actual flow of funds. Mixing transactions between entities can make an otherwise well-run investment much harder to review.
Our advice is to review the entity, property, and account setup before a major transaction closes. That simple check can help prevent misposted entries, unclear ownership records, and extra cleanup at tax time.
For investors with multiple properties, strong real estate investor bookkeeping is less about making more entries and more about making sure each entry lands in the right place.
Key Takeaways
- A 1031 exchange needs clear and well-organized financial records.
- Track the sale, exchange funds, costs, debt, and replacement property.
- Keep the old property’s basis and depreciation history.
- Do not assume every closing cost is a normal business expense.
- The replacement property’s tax basis may differ from its purchase price.
- Keep your bookkeeper, CPA, and qualified intermediary aligned.
FAQs
A bookkeeper can track and organize the financial activity, but your CPA or tax advisor should determine the tax treatment of the exchange.
Exchange funds should be tracked separately and matched to the qualified intermediary’s records and closing documents.
The old property’s depreciation history should be retained because it may be relevant when determining the tax basis of the replacement property.
Cash or other non-like-kind property received in an exchange may result in taxable gain. Your tax advisor should review the transaction before the books are finalized.
Start before the sale closes. Early review can help catch missing basis records, loan details, closing costs, or other transaction data before they become harder to verify.
optional anymore
on running the business