QuickBooks for law firms can show why a busy legal practice still struggles to make a profit. A case may bring in $12,000 in fees, yet court costs, expert charges, unpaid invoices, and staff time can eat into that income. Without clear records, partners may see the revenue but miss the true cost of the work.
The answer lies in tracking each dollar from the first client payment to the final bill. QuickBooks for law firms can record legal fees, case costs, and payments in one accounting system. But firms must also keep client funds separate, check trust balances, and follow state bar rules. The goal is not just clean accounts; it is better insight into which matters earn money and where cash gets stuck.
What You Will Learn From This Blog
- How to track case costs, client bills, and unpaid fees.
- How law firm trust accounting keeps client funds apart from firm income.
- How to work out profit by case and client.
- Which financial KPIs reveal billing delays and rising costs.
- How to avoid common errors in legal accounting.
- How Meru Accounting provides accounting services for law firms.
How QuickBooks for Law Firms Supports Client Cost Tracking and Profitability Analysis
A law firm can win a case, bill the client, and still face a cash gap if expenses remain unbilled or invoices go unpaid. QuickBooks for law firms gives staff a way to track these items by client or matter, provided the records use clear names and consistent cost codes.
For example, a case may bring in $6,000 in fees and $800 in court and expert costs. If the firm misses those costs in its review, the reported profit may look higher than it is. Law firm trust accounting needs a separate process because money held for clients is not the same as income earned by the firm.
Key QuickBooks Features for Legal Practice Management
Client and Matter Tracking
Give each client and legal matter a clear record so staff can trace fees and costs to the right case. A consistent naming system also makes it easier to compare open matters and find entries that need review.
Expense and Bill Tracking
Record court fees, expert charges, travel, and other costs with the date, payee, purpose, and matter name. These details let staff check each charge before billing it or treating it as a firm expense.
Invoice and Payment Records
QuickBooks for law firms can record invoices, payments, and unpaid balances. Staff should compare each bill with the fee agreement and work done before sending it to a client.
Financial Reports
Profit and loss reports show income and spending, while accounts receivable reports reveal unpaid bills. Matter-level results depend on the tracking features available and the way staff enters the data.
Bank Reconciliation
Compare the entries in QuickBooks with the bank statement to find missing payments, duplicate entries, or bank fees. Regular checks make month-end reports more reliable.
How to Track Client Costs in QuickBooks for Law Firms
Recording Billable and Non-Billable Client Expenses
Not every case cost should go on a client invoice. QuickBooks for law firms can track billable costs, such as an allowed $200 filing fee, separately from firm costs, such as office rent.
Assigning Expenses to Individual Clients and Legal Matters
Enter each expense against the right client and matter when the cost occurs. A $300 expert fee for one case should not appear under another client’s records, as this can distort the profit report.
Tracking Reimbursable Costs and Client Disbursements
Record costs paid on a client’s behalf and check the fee agreement before billing them. Law firm trust accounting rules may affect how certain funds must be handled, so staff should not treat every client payment as a normal expense or fee.
Reconciling Client Invoices, Payments, and Outstanding Balances
Compare each invoice with the amount received and the balance still due. If a firm bills $1,200 and collects $900, the remaining $300 should stay open until payment or an approved adjustment is recorded.
Law Firm Trust Accounting: Managing Client Funds and Compliance
Understanding Trust Accounts and Client Fund Separation
A client advance is not automatically income for the firm. Law firm trust accounting keeps client money apart from firm funds, so a $5,000 deposit must be recorded and handled under the fee terms and applicable rules.
Recording Trust Deposits, Withdrawals, and Transfers
Record every deposit, payment, and transfer with its date, amount, client, and purpose. QuickBooks for law firms must be set up with care, so trust activity does not appear as earned revenue or routine operating costs.
Reconciling Trust Bank Accounts With Individual Client Ledgers
The trust bank balance, trust account balance in the ledger, and total of all client balances must agree after valid timing items are checked. If the bank shows $20,000, the combined client ledgers should account for that full amount.
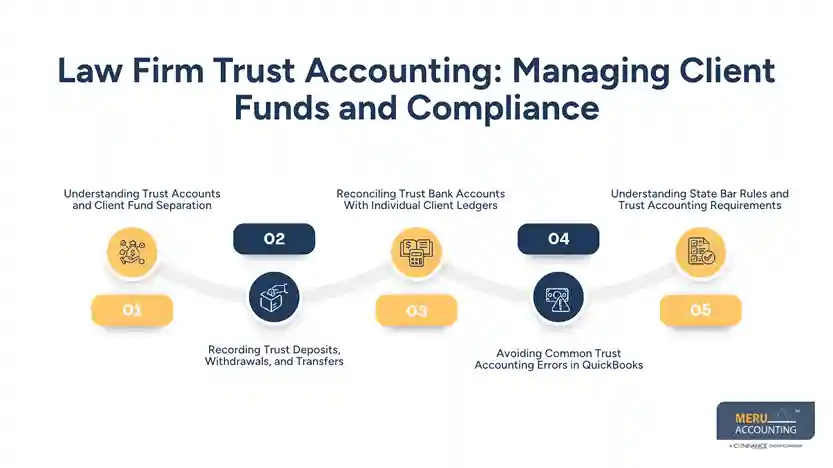
Avoiding Common Trust Accounting Errors in QuickBooks
Never use one client’s funds to cover another client’s costs or the firm’s bills. Law firm trust accounting also calls for prompt review of unexplained balances, missing entries, and transfers without clear records.
Understanding State Bar Rules and Trust Accounting Requirements
Trust account rules vary by state and may cover records, account types, client statements, and transfers. Firms should check their state bar’s current rules and seek qualified advice when a transaction or process is unclear.
optional anymore
on running the business
How to Measure Matter Profitability Using QuickBooks
Tracking Revenue and Expenses by Legal Matter
QuickBooks for law firms can group fees and costs by matter when staff uses the same tracking rules. A case with $8,000 in revenue and $2,500 in direct costs has $5,500 left before lawyer time and shared overhead.
Calculating Profit Margins for Individual Cases
Divide profit by revenue and multiply by 100 to find the margin. If a matter earns $10,000 and costs $7,000 in total, its profit margin is 30%, as long as all relevant costs are included.
Comparing Billable Hours With Matter Revenue
Compare the fees earned on a case with the time spent by lawyers and staff. If a lawyer spends 40 hours on a matter that earns $4,000, the revenue is $100 per hour before costs and overhead.
Identifying Unprofitable Clients and High-Cost Legal Matters
Look for matters with rising costs, late payments, repeated write-offs, or more hours than planned. High fees alone do not mean a case generates a strong profit if it takes too much time or leaves costs unpaid.
Using Job Costing and Class Tracking for Profitability Analysis
QuickBooks for law firms may offer projects, classes, or other tracking tools, based on the version and plan. Choose a method that fits the firm’s work, apply it in the same way across cases, and check the report before making decisions.
Key Financial KPIs Every Law Firm Should Track
Realization Rate and Collection Rate
The realization rate shows how much of the value of billable work becomes billed fees. QuickBooks for law firms can track billing records and payment data to reveal gaps between work done, fees billed, and cash collected.
Revenue per Lawyer and per Matter
Divide fee revenue by the number of lawyers or matters in the same period. Use clear rules each month so partners can compare results without drawing false conclusions from uneven data.
Average Accounts Receivable Days
This measure shows how long clients take to pay, on average. QuickBooks for law firms can track outstanding invoices and payment dates, helping billing teams identify overdue balances.
Work in Progress (WIP) and Unbilled Client Costs
WIP is work done but not yet billed, while unbilled client costs are expenses that may need to be charged to clients. Review both each month to spot work and costs that have sat outside invoices for too long.
Operating Profit Margin and Overhead Ratio
The operating profit margin in QuickBooks for law firms shows the share of revenue left after operating costs. The overhead ratio shows how much income goes to costs such as rent, software, and office staff, making it easier to spot rising spending.
Client Acquisition Cost and Revenue per Client
Client acquisition cost measures what the firm spends to gain a new client, while revenue per client shows fees earned over a set period. Review both with care, as a client with high revenue may also need more time and resources.
Common QuickBooks Accounting Mistakes Law Firms Should Avoid
Mixing Client Trust Funds With Operating Funds
When using QuickBooks for law firms, keep client trust funds in the proper account and do not record them as earned fees before they are due. Law firm trust accounting errors can put client money at risk and may breach state rules.
Misclassifying Client Costs and Reimbursable Expenses
Use clear account types and matter tags for costs paid by the firm or on behalf of clients. Wrong labels can distort reports and lead to incorrect client bills.
Overlooking Unbilled Expenses and Outstanding Invoices
Review open invoices and unbilled costs at month-end. QuickBooks for law firms can show unpaid balances, but staff must check that all valid fees and costs have been entered and billed under the firm’s terms.
Relying on Inaccurate Matter-Level Profitability Reports
QuickBooks for law firms reports may be wrong if staff miss time, costs, write-offs, or shared overhead. Check the source entries and cost rules before using profit figures to set fees or plan future work.
Skipping Monthly Bank and Trust Account Reconciliation
Reconcile operating and trust accounts each month, or as often as the rules require, and review each difference. Regular checks can catch duplicate entries, missin
How Meru Accounting Provides Accounting Services for Law Firms
- Expense Tracking: Meru Accounting reviews business expenses and client costs to keep financial records clear and accurate.
- Accounts Payable and Receivable: Our team tracks vendor bills, client invoices, payments, and outstanding balances.
- Bank Reconciliation: We compare bank records with accounting entries to identify missing transactions and errors.
- Payroll and Financial Reporting: We maintain payroll records and prepare financial reports for better cost and income review.
- Matter-Level Accounting: Our team reviews client costs, invoices, and matter records to provide a clearer view of legal expenses and revenue.
- Law Firm Trust Accounting: We can review trust-related accounting records, while the law firm remains responsible for following state bar rules, maintaining client ledgers, and approving trust transactions.
Our Expert Perspective
Law firm profitability depends on accurate matter-level records, timely expense tracking, and regular reviews of unpaid invoices. QuickBooks for law firms can provide useful financial insights, but reliable reports require consistent data entry, proper cost allocation, and regular reconciliation. Firms should also monitor collection rates, unbilled expenses, and overhead while maintaining separate client trust records and following applicable state bar rules.
Key Takeaways
- QuickBooks for law firms can track legal fees, client costs, invoices, and payments when records are set up well.
- Law firm trust accounting must keep client money separate from firm funds and follow state bar rules.
- Matter-level reports need accurate cost, time, and revenue data to show a fair view of profit.
- Track collection rates, unpaid bills, WIP, overhead, and profit margins each month.
- Regular bank and trust account checks can catch errors before they cause larger issues.
- Meru Accounting provides bookkeeping and accounting services for law firms that need clear records and reports.
FAQs
QuickBooks for law firms can record billable expenses, client payments, legal fees, and matter costs to keep financial records clear.
QuickBooks for law firms can track matter revenue and expenses to estimate profit when staff assigns costs and fees to the correct cases.
QuickBooks can record trust deposits and withdrawals, but firms must maintain individual client ledgers and follow applicable state bar rules.
Law firms should track collection rates, realization rates, revenue per lawyer, accounts receivable days, unbilled costs, and operating profit margins.
Law firms should compare trust bank statements, accounting balances, and individual client ledgers regularly to identify and resolve differences.
optional anymore
on running the business