A law firm’s financial health isn’t measured by the number of cases it wins or the fees it bills. What matters is how well it turns that work into cash it can use. Court delays, disputed invoices, slow-paying clients, and rising overhead can make it hard to keep money moving, even when business is good. That’s why law firm cash flow management needs to be part of running a successful practice, not just a task for the bookkeeper.
The goal is to build a firm that can meet its bills, pay its team, and take on new work without putting pressure on its finances. In this blog, we’ll look at practical ways to improve collections, keep costs in check, and use cash flow forecasting for small law firms to make better financial plans.
What You Will Learn From This Blog
- What law firm cash flow management means and why it matters.
- Why small law firms face cash flow gaps.
- How to improve client payments and control costs.
- How cash flow forecasting for small law firms helps plan for future needs.
- Which key financial metrics help track the firm’s cash position.
- How expert accounting support can help law firms manage cash flow.
What Is Law Firm Cash Flow Management?
Law firm cash flow management is the process of tracking, planning, and managing the money that comes into and goes out of a law firm. It helps firms make sure they have enough cash to pay staff, cover office costs, pay vendors, and meet tax bills.
For law firms, cash flow can be hard to manage because work and payments do not always follow the same timeline. A firm may bill a client in one month but not get paid until the next. Some cases may take months to close, while other clients may pay late or in parts.
It is also vital to keep client trust funds apart from firm funds. Money held in trust does not belong to the firm and must not be used to pay its own bills. Firms should follow the trust account rules that apply in their state and keep clear records of all client funds.
Cash flow vs. profit
Profit and cash flow are not the same. Profit shows what a firm earns after costs are taken out. Cash flow shows the money that has been paid in and paid out during a set time.
For example, a firm may bill $30,000 in a month but collect only $18,000. If its costs are $22,000, it may show a profit based on work done, yet face a $4,000 cash gap for that month. This is why firms need to track both income and cash on hand.
Why Do Small Law Firms Struggle with Cash Flow?
Small firms often have fewer cash reserves than large firms. A few late payments or a sudden rise in costs can put pressure on their day-to-day work. Some common causes include:
- Late client payments: Clients may take weeks or months to pay their bills. This leaves firms with less cash to cover staff pay, rent, and other costs.
- Long case timelines: Some legal matters take months or even years to close. Firms may need to spend time and money on a case well before they receive the full fee.
- High fixed costs: Rent, staff pay, legal tools, insurance, and office costs must be paid on time, even when client payments are slow.
- Poor billing habits: Late invoices, unclear fee terms, and missed follow-ups can delay payments. Small firms may also lack a set process to review unpaid bills.
- Unplanned costs: Court fees, expert fees, software renewals, and tax bills can add pressure when firms have not set cash aside.
Good law firm cash flow management starts with knowing where these gaps come from. Once firms spot the cause, they can take steps to reduce the risk.
optional anymore
on running the business
How to Improve Law Firm Cash Flow Management
A steady cash flow depends on more than getting new clients. Firms also need a clear plan to bill on time, collect fees, and keep costs in check. These steps can help:
1. Set clear payment terms
Explain fees, due dates, retainers, and payment terms before work begins. Put the terms in the client agreement so both sides know what to expect. Clear terms can reduce payment delays and avoid disputes over bills.
2. Send invoices on time
Do not wait until the end of the month to bill for work that can be billed sooner. Set a regular billing cycle and send clear invoices with a list of work done, fees charged, and the due date.
3. Follow up on unpaid bills
Review unpaid invoices each week. Send a polite reminder before and after the due date. For older bills, contact the client to ask when payment can be made. Keep a record of each follow-up.
4. Make payments easy
Offer secure ways for clients to pay, such as bank transfers and online payment options. Make sure the payment steps are clear and that clients know where to send funds.
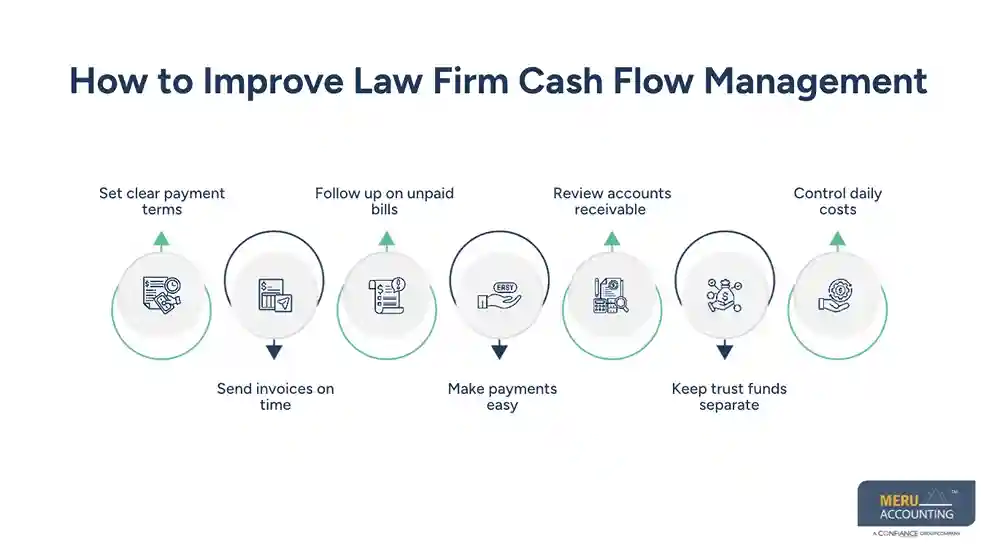
5. Review accounts receivable
Accounts receivable (A/R) is the money clients owe the firm. Review A/R each month to see which bills are due, which are late, and which may need more follow-up. This helps firms act before old bills turn into bad debt.
6. Keep trust funds separate
Keep client trust funds in the right trust account and never count them as cash the firm can use. Review trust records and bank balances on a set schedule. Follow state bar rules for trust account records and checks.
7. Control daily costs
Check monthly costs such as rent, payroll, software, travel, and office supplies. Look for tools or plans the firm no longer needs. Cut costs with care so that savings do not affect client service or work quality.
These steps make law firm cash flow management more steady and help firms use their cash with care.
How to Create Cash Flow Forecasting for Small Law Firms
Cash flow forecasting for small law firms helps owners estimate how much money will come in and go out over a set time. It gives them a clear view of future cash needs and helps them plan for slow months, tax bills, and high costs.
A useful forecast should be based on real payment data, not just the total value of work billed. Here is how to build one:
1. Estimate cash coming in
Start with fees the firm expects to collect. Review past client payments, open invoices, payment plans, and signed fee terms. Use realistic dates for when funds may arrive. Do not treat every open invoice as cash that will be paid on time.
2. List all expected costs
Add fixed costs such as rent, staff pay, insurance, and software. Then add costs that may change, such as court fees, travel, expert fees, and office supplies. Include tax payments and loan bills where they apply.
3. Set a time frame
Start with a weekly forecast for the next 8 to 13 weeks. This helps firms spot near-term cash gaps. A monthly forecast for the next 6 to 12 months can help with hiring, growth, and other large plans.
4. Plan for slow payments
Do not assume all clients will pay by the due date. Use past payment trends to estimate delays. You can also make a second forecast based on lower fee collections to see how the firm would cope.
5. Compare the forecast with actual results
At the end of each week or month, compare planned cash with the amount that came in and went out. Find out why the figures differ and update the next forecast.
Example: A simple monthly cash flow forecast
Cash flow item | Amount |
Opening cash balance | $20,000 |
Expected client collections | $25,000 |
Total cash available | $45,000 |
Staff pay and benefits | $16,000 |
Rent and utilities | $4,000 |
Software and insurance | $2,500 |
Other operating costs | $3,500 |
Total cash outflow | $26,000 |
Closing cash balance | $19,000 |
Illustrative figures only. The forecast assumes all expected collections arrive within the month.
This example shows why cash flow forecasting for small law firms should track opening cash, expected collections, and planned costs. If client payments fall short, the firm can review spending or follow up on unpaid bills before cash gets too low.
Key Financial Metrics Every Law Firm Should Monitor
Tracking the right figures helps firms see if their cash plan is working. These metrics can give owners a better view of income, costs, and payment trends.
Financial metric | What it tells you |
Accounts receivable aging | Shows how long client bills have been unpaid. |
Collection rate | Shows how much of the amount billed has been paid. |
Realization rate | Shows how much of the value of work done is billed to clients. |
Monthly cash flow | Tracks cash received and paid during the month. |
Operating expenses | Shows the cost of running the firm. |
Cash reserve | Shows how much cash is on hand to cover future costs. |
Review these figures each month and look for changes. For example, a rise in bills that are more than 60 days old may point to weak follow-up or payment issues. A rise in monthly costs may also call for a review of spending.
Law Firm Cash Flow Management Services by Meru Accounting
A useful cash flow plan depends on knowing which client bills are likely to be paid, what expenses are coming due, and how much cash the firm can use. Meru Accounting provides dedicated accounting support to help law firms maintain this financial oversight.
Our services for law firms include:
- Cash Flow Forecasting: Prepare cash flow projections using expected client collections, recurring costs, and upcoming financial obligations.
- Accounts Receivable Management: Maintain aging reports, track outstanding legal fees, and monitor collection trends.
- Legal Bookkeeping: Maintain records of legal fees, client payments, operating expenses, and other financial transactions.
- Trust Account Reconciliation: Reconcile client trust accounts and maintain accurate records of client funds.
- Cash Flow and Financial Reporting: Provide regular reports on cash positions, income, expenses, and changes in working capital.
- Expense and Payroll Tracking: Monitor recurring overhead, payroll costs, and other scheduled payments for better cash planning.
Our trained professionals bring multi-industry experience and a structured review process to accounting work. We help law firms maintain reliable financial records and get the reports they need to make informed decisions.
Our Expert Insight
One area law firms often overlook is the link between attorney workload and cash flow. A firm may take on more cases and hire additional staff before those cases generate enough fees to cover the added cost. This can put pressure on cash reserves, even when the firm has a strong pipeline of new work.
We recommend reviewing staffing costs against billable hours, fee arrangements, and expected case timelines before expanding the team. This helps law firm owners judge whether new work can support the added expense and avoid hiring ahead of revenue.
Key Takeaways
- Law firm cash flow management helps firms track income, costs, and cash on hand.
- Billed fees are not the same as cash collected from clients.
- Clear payment terms, timely bills, and regular follow-ups can improve collections.
- Cash flow forecasting for small law firms helps owners plan for future costs and slow months.
- Tracking A/R, collection rates, costs, and cash reserves can help spot risks early.
- Good books and clear reports support better financial choices.
FAQs
Common causes include long case cycles, delayed fee payments, unbilled attorney time, high payroll costs, and poor expense planning. Contingency fee practices may also face long gaps between case costs and fee receipts.
A common planning target is three to six months of essential operating expenses. The right amount depends on the firm’s size, fee structure, case cycle, and payment history. Firms with uneven revenue may need a larger reserve.
Contingency fee firms may pay case-related costs for months or years before receiving fees. They should account for case expenses, expected settlement timelines, and the risk of cases that do not result in recovery when planning cash needs.
Unearned client retainers generally must be held in a trust account until earned under the applicable fee agreement and state bar rules. They should not be counted as available operating cash. Firms must track earned and unearned fees correctly.
A law firm may benefit from outsourced accounting when it lacks timely financial reports, struggles to track receivables, or needs regular cash flow forecasts. An experienced accounting team can provide bookkeeping, reconciliation, financial reporting, and forecasting support.
optional anymore
on running the business