Year-end can reveal problems that stay hidden during the year. A real estate CPA may find that one property has missing expenses, another has an old loan balance, and a third has improvement costs booked the wrong way. With several properties, these small issues can add up fast.
A multi-property company needs more than a basic year-end bookkeeping check. Each property should have accurate income, expenses, debt, asset, and cash records, while the company’s books should also reflect transfers and shared costs correctly. A CPA for real estate companies can help review these records, fix gaps, and get the books ready for tax work and the year ahead.
What You Will Learn From This Blog
This blog covers:
- What year-end accounting means for a multi-property real estate firm
- Key steps to add to your year-end close
- How to review each property
- Common errors that can affect your books
- When to bring in a real estate CPA
- How a CPA for real estate companies can support year-end work
- What records to keep ready for tax and review work
What Year-End Accounting Means for a Multi-Property Real Estate Company
Year-end accounting is the process of checking and closing your books for the year. For a multi-property firm, that work must be done at both the property and company level.
Each asset should have clear income and cost data. You also need to make sure the main books show the right cash, debt, assets, and equity.
A real estate CPA can review these records and look for items that need an update before the year is closed.
This may include:
- Rent and other income
- Repairs and upkeep
- Property tax
- Insurance
- Loan payments
- Interest costs
- Capital work
- Vendor bills
- Owner draws
- Cash held for each property
The goal is not just to make the books balance. The goal is to make sure each balance has a clear source and is backed by good records.
This is more vital when one firm owns many assets. A cost that belongs to Property A should not be left in Property B’s books. Shared costs must also be split in a fair and clear way.
If each property has its own books, reports can show which assets earn cash and which ones need more spending. This gives owners a better base for tax work and plans for the next year.
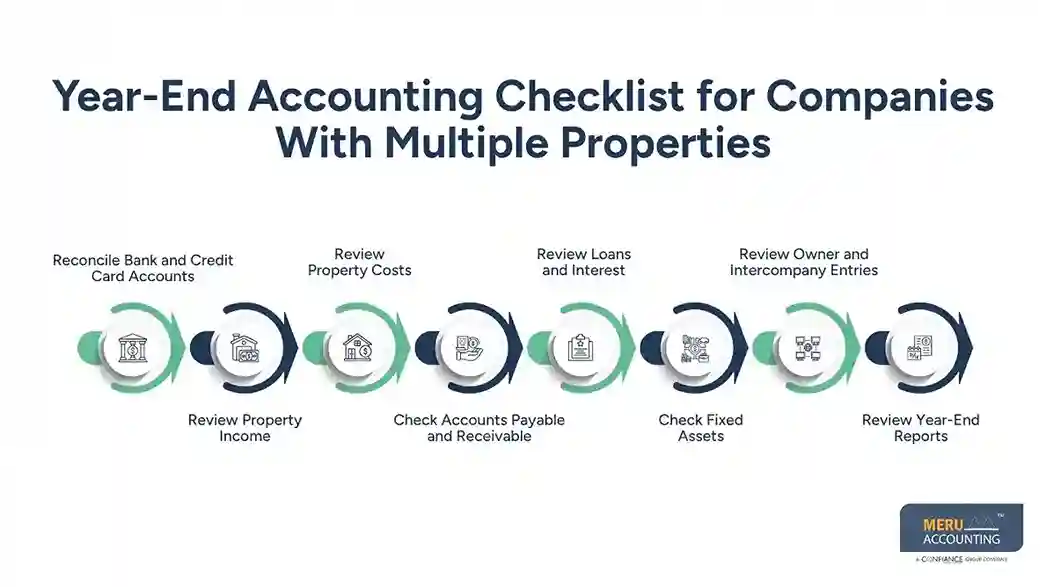
Year-End Accounting Checklist for Companies With Multiple Properties
A clear checklist can help you close the year with fewer gaps. Your real estate CPA can use the same list to guide the review.
Reconcile Bank and Credit Card Accounts
Match each bank and card account to the books. Look for old checks, open items, bank fees, and entries that may have been missed.
Review Property Income
Check rent, fees, late charges, and other income. Make sure all income for the year is in the right period and tied to the right property.
Review Property Costs
Scan costs by property. Check items such as rent admin, repairs, tax, insurance, utilities, and vendor fees.
Check Accounts Payable and Receivable
Review bills that have not been paid and funds that are still due. Make sure old balances have a clear reason.
optional anymore
on running the business
Review Loans and Interest
Match loan balances to lender records. Check the split between loan paydown and interest so the books show each part in the right place.
Check Fixed Assets
Review new buys, major upgrades, and other costs that may need to be added to the asset list. A real estate CPA can help review how such costs should be treated for tax and book use.
Review Owner and Intercompany Entries
Check all owner funds, draws, and transfers. If funds move from one entity or property to another, make sure both sides of the entry agree.
Review Year-End Reports
Run the profit and loss, balance sheet, cash flow, and key property reports. Review large changes from the prior year.
This list gives your CPA for real estate companies a strong base for the year-end review.
How to Review Each Property Before Year-End
A multi-property firm should not treat all assets as one large pool. Each property needs its own review.
Start With Property Income
Check rent and other income against rent rolls, bank records, and property reports. Look for missing deposits, duplicate entries, or income posted to the wrong property.
Review Repairs and Capital Work
This is one area where errors can have a big impact. Routine repairs and major upgrades may not be handled in the same way for accounting or tax work.
Keep invoices, contracts, and proof of payment for major work. A real estate CPA can then review the records and decide what needs further tax review.
Check Property Tax and Insurance
Make sure property tax and insurance costs are posted to the right asset. Also check for bills paid in advance or costs that cover more than one period.
Review Tenant Balances
If the company rents units, check unpaid rent, tenant credits, and security deposits. Old balances should not sit on the books without review.
Review Loans Tied to the Property
Compare each loan balance with the latest lender record. Check the amount of principal paid, interest paid, and any new debt or refinance activity.
Compare Property Results
Once each asset is clean, compare results across the portfolio. Look at income, costs, net cash, and major changes.
This can help owners spot assets that need a rent review, cost cut, new plan, or more capital.
Common Year-End Accounting Mistakes in Multi-Property Businesses
Year-end errors often come from poor tracking rather than hard math. The more properties a firm owns, the easier it is for small gaps to spread across the books.
Mixing Property Transactions
A bill for one asset may be paid from a bank account used by another. If the entry is not moved to the right property, the reports can give a false view of both assets.
Misclassifying Repairs and Improvements
Large work may be booked as a normal repair without a full review. This can affect both the books and tax records.
Leaving Loan Balances Unchecked
A loan may be paid each month, yet the book balance can still be wrong. It is wise to match the balance to lender data at year-end.
Missing Depreciation Records
Asset and upgrade records must stay up to date. Missing data can make tax prep harder and may lead to more work later.
Ignoring Old Balance Sheet Items
Old deposits, vendor credits, loans, and other balances should not be left in place just because they have been there for years.
Mixing Entity Records
If several LLCs own the properties, each entity needs clear records. Transfers between entities should be tracked and matched.
Closing Before All Data Is In
Some firms close the books too soon. Late bills, tax bills, loan data, and other year-end items may then need changes after the close.
A real estate CPA can help build a close process that gives each item a clear review point.
When Should a Multi-Property Company Hire a Real Estate CPA?
A small property owner may manage basic books with a bookkeeper and standard software. But the need for expert review often grows as the portfolio gets larger.
You may want a real estate CPA when:
- You own several properties
- Each property has its own LLC
- You have many rental units
- You buy or sell property often
- You refinance or add new debt
- You have major repair or build costs
- You use a 1031 exchange
- Your books have many old balances
- You need property-level reports
- Tax work takes more time each year
A CPA for real estate companies can bring tax and accounting work into one process. This can help reduce gaps between your books and tax records.
The right time to hire a real estate CPA is not only when a problem comes up. Year-end planning is often easier when the CPA has time to review key items before the books are closed.
Real Estate CPA Services From Meru Accounting
At Meru Accounting, we help real estate firms keep clean books across a multi-property portfolio. Our real estate CPA services are built around clear records, timely reports, and year-end readiness.
We can help with:
- Property-level bookkeeping
- Bank and credit card reconciliation
- Income and expense tracking
- Accounts payable and receivable
- Loan and debt account review
- Fixed asset records
- Property-level financial reports
- Multi-entity accounting support
- Year-end book cleanup
- Tax-ready accounting records
Our team can also work with the accounting setup you already use. The aim is to keep your books clear and easy to review as your portfolio grows.
For owners who need a CPA for real estate companies, good year-end work should go beyond data entry. It should give you records that you can use for tax work, cash planning, and property decisions.
Our Expert Insight
From our experience, one of the first things to check at year-end is whether property-level results actually match the underlying records. A property can show a healthy profit while missing loan costs, improvement expenses, or owner-funded payments.
We also look closely at transfers between properties and related LLCs. These entries are easy to overlook and can leave balances that don’t match across the books. Catching those issues before year-end close makes tax preparation much cleaner.
Key Takeaways
- Multi-property firms need both property-level and company-level year-end reviews.
- Reconcile cash, debt, income, costs, assets, and equity before closing the books.
- Keep each property’s records separate and easy to trace.
- Review major repairs, upgrades, loans, and tax-related items with care.
- Do not leave old or unclear balance sheet items unresolved.
- A real estate CPA can help review complex accounting and tax-related items.
- A CPA for real estate companies can also help create a year-end process that scales with your portfolio.
- Clean year-end books give owners a better base for tax work and new-year plans.
FAQs
Yes. A separate P&L for each property makes it easier to compare income, operating costs, and profitability across the portfolio.
Major improvements are generally treated differently from routine repairs. Your real estate CPA can review the cost, determine the proper classification, and ensure it is recorded correctly for tax purposes.
Security deposits that may be returned to tenants are generally recorded as a liability, not rental income. The accounting treatment can change if a deposit is later kept for damages or unpaid rent.
The payment should be recorded so both entities show the correct expense and balance. This is especially important when several properties operate under separate LLCs.
Yes. A real estate CPA can review depreciation schedules, additions, disposals, and changes in property basis before the tax return is prepared.
optional anymore
on running the business